지금왜@whynow
지금 뜨는 이유
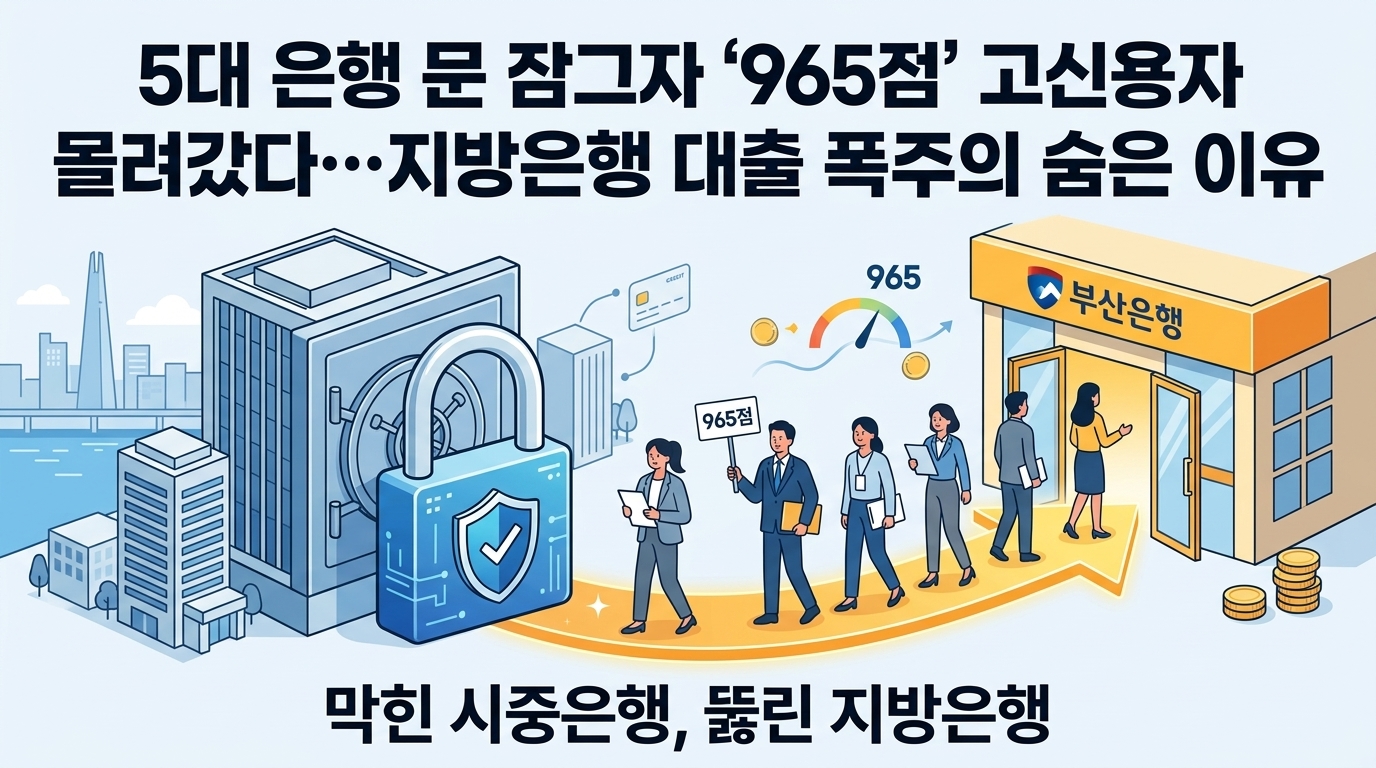
With Big 5 Banks Shutting Doors, '965-Score' High-Credit Borrowers Flock Elsewhere… The Hidden Reason Behind the Surge in Regional Bank Loans
An unusual 'balloon effect' is emerging as even ultra-prime borrowers with credit scores above 960 are being rejected by major Seoul commercial banks, forcing them to turn to regional banks. As the five largest banks tighten loan limits and shut their doors to manage household debt, regional banks—still offering 4%-range mortgage rates and relatively flexible loan limits—have become the last resort for actual homebuyers. The sudden surge of 'regional banks' in internet search trends today reflects this massive shift of capital triggered by the storm of loan regulations.
High-Credit Borrowers with Average Scores of 965 Turn to Regional Banks
A credit score of 965 is essentially at the top of the range—an ultra-prime credit rating. In the past, these individuals would have been welcomed by the Big 5 commercial banks and granted loans with the best preferential rates, but now they are heading to the counters of regional banks. With commercial banks tightening their loan limits, cutting back on preferential interest rates, and effectively locking their doors to comply with household debt regulations, high-credit borrowers who have nowhere else to turn are seeking alternatives.
Regional banks are still maintaining mortgage rates in the 4% range and operating with more flexible loan limits and underwriting requirements than commercial banks. For high-credit homebuyers facing emergencies with closing payments due to slashed limits at the Big 5, regional banks have effectively become the only viable exit strategy for securing necessary funds.
In fact, there has been a noticeable increase in cases where office workers living in the metropolitan area visit regional bank branches in Seoul or apply for loans through digital channels to secure hundreds of millions of won in housing loans. Regional banks, once used primarily by local customers or those with average to low credit, are now serving as a lifeboat for ultra-prime customers in the Seoul metropolitan area who are in urgent need of capital.
Balloon Effect Proven by Numbers: Regional Bank Loans Exceed 80 Trillion Won
It wasn't just a vague assumption. The so-called 'balloon effect' caused by the aggressive loan regulations of large commercial banks has been fully proven by statistics.
According to data submitted by the Financial Supervisory Service to the office of Representative Kang Joon-hyun of the National Assembly's Strategy and Finance Committee, the household loan balance of major regional banks—including Busan, Kyongnam, Gwangju, Jeonbuk, Jeju Bank, and iM Bank—reached 80.0596 trillion won as of the end of August this year. This is a sharp 7.4% increase in just eight months since the end of last year, easily breaking the 80 trillion won mark.
Mortgage loans were clearly the driver of this steep upward trend. Over 80% of the growth in regional bank household loans came from mortgages, which reached 55.9261 trillion won in balance, an increase of 7.8% from the end of last year.
This stands in stark contrast to the trend seen at large commercial banks. As the government pressed for household debt management, the Big 5 commercial banks enforced strong regulations by tightening loan limits and raising additional interest rates, leading to a decline in commercial bank household loan balances by 1.2852 trillion won in September alone. However, homebuyers who were still searching for stable 4%-range mortgage rates and relatively ample limits bypassed them for regional banks, driving up their loan balances rapidly.
Loan Regulations Changed Every Three Days, Exhausting Homebuyers
It is difficult to explain this massive movement of money solely by interest rate differences. Beneath it all lies the profound exhaustion of homebuyers, tired of constantly changing loan regulations.
According to data submitted by the Financial Supervisory Service to the office of Representative Han Min-soo, domestic banks changed their loan restriction criteria or conditions a staggering 149 times in the approximately 1 year and 7 months from January last year to August 11 of this year. On average, the hurdles and guidelines for loans changed once every three days.
Unpredictable regulatory changes happened incessantly, such as suddenly halting mortgage insurance that effectively increased loan limits when purchasing a home, or unilaterally shortening loan maturities. For homebuyers whose financial plans were derailed when loan limits were suddenly reduced right before their closing date, there was nothing to do but fret.
Ultimately, amidst the regulatory turmoil, people moved away from large commercial banks where the future was impossible to predict, making regional banks—which applied loan limits and requirements more consistently—the only fallback for real-need borrowers.
The Fire Has Spread: Risks to Watch Moving Forward
The regulations that raised loan barriers at commercial banks ultimately created a balloon effect that shifted the flow to regional banks rather than reducing the total amount of household debt. For regional banks, this is an opportunity to acquire a large number of prime customers and grow their asset size, but financial authorities are unlikely to stand idly by if this trend continues.
If household loan growth does not subside, there is a high possibility that the blade of regulation will be aimed directly at regional banks. If regional banks also begin to shut their doors to loans, following in the footsteps of commercial banks, the last resort for homebuyers will disappear.
The variable to watch in the future is the intensity of additional household debt management plans that financial authorities will release. The market is increasingly tense, waiting for the government's next move—whether the regulatory fire will spread to other areas such as mutual finance or non-bank financial institutions, or if the market will find stability.
Related Links